
In a U.S. venture-backed corporation, the founder vesting schedule standard is a four-year vesting period with a one-year cliff. Under this structure, 25% of a founder's shares vest on the first anniversary of their start date, while the remaining 75% accrues monthly or quarterly over the next 36 months. Founders typically receive restricted stock upfront. The company then retains a contractual right to repurchase any unvested shares if the founder leaves. EverythingStartups provides actionable data to help ecosystem players discover the next generation of companies, so you can use our investor intelligence tools to prepare for financing and governance discussions before sitting down with your board. Understanding this market baseline gives you a framework for negotiation, even though we do not set or predict the specific legal terms your company will adopt.
Defining the Four-Year Vesting Standard for Founders
The Four-Year, One-Year-Cliff Baseline
Startup employee equity commonly vests over time. An equity guide by Orrick identifies four years with a one-year cliff as the market standard for employee equity. The cliff supports commitment to the company because an employee who leaves before the first year does not retain equity that has not vested. After the first year, the initial 25% vests, followed by monthly vesting for the remainder.
A Negotiated Market Convention
Section 202 of the Delaware Code addresses restrictions on the transfer and ownership of securities, including certificate and notice requirements, and it does not set a four-year vesting schedule.
If you are negotiating a pre-seed funding valuation, the vesting timeline often appears in the term sheet alongside the financial numbers. From there, you can negotiate the start date, the acceleration terms, and the repurchase definitions.
Applying the Framework to U.S. Restricted Stock
This framework applies specifically to founder restricted stock in a U.S. venture-backed C-corporation. Other entity types and equity regimes operate differently, such as LLC interests that involve complex profits interests or capital interests with distinct tax rules. Non-U.S. jurisdictions have their own tax triggers making U.S.-style restricted stock inefficient. Employee stock options also follow different mechanical rules, even when they use the same four-year timeline.
Mechanics of the Four-Year, One-Year-Cliff Schedule
Cliff Mechanics and Vesting Milestones
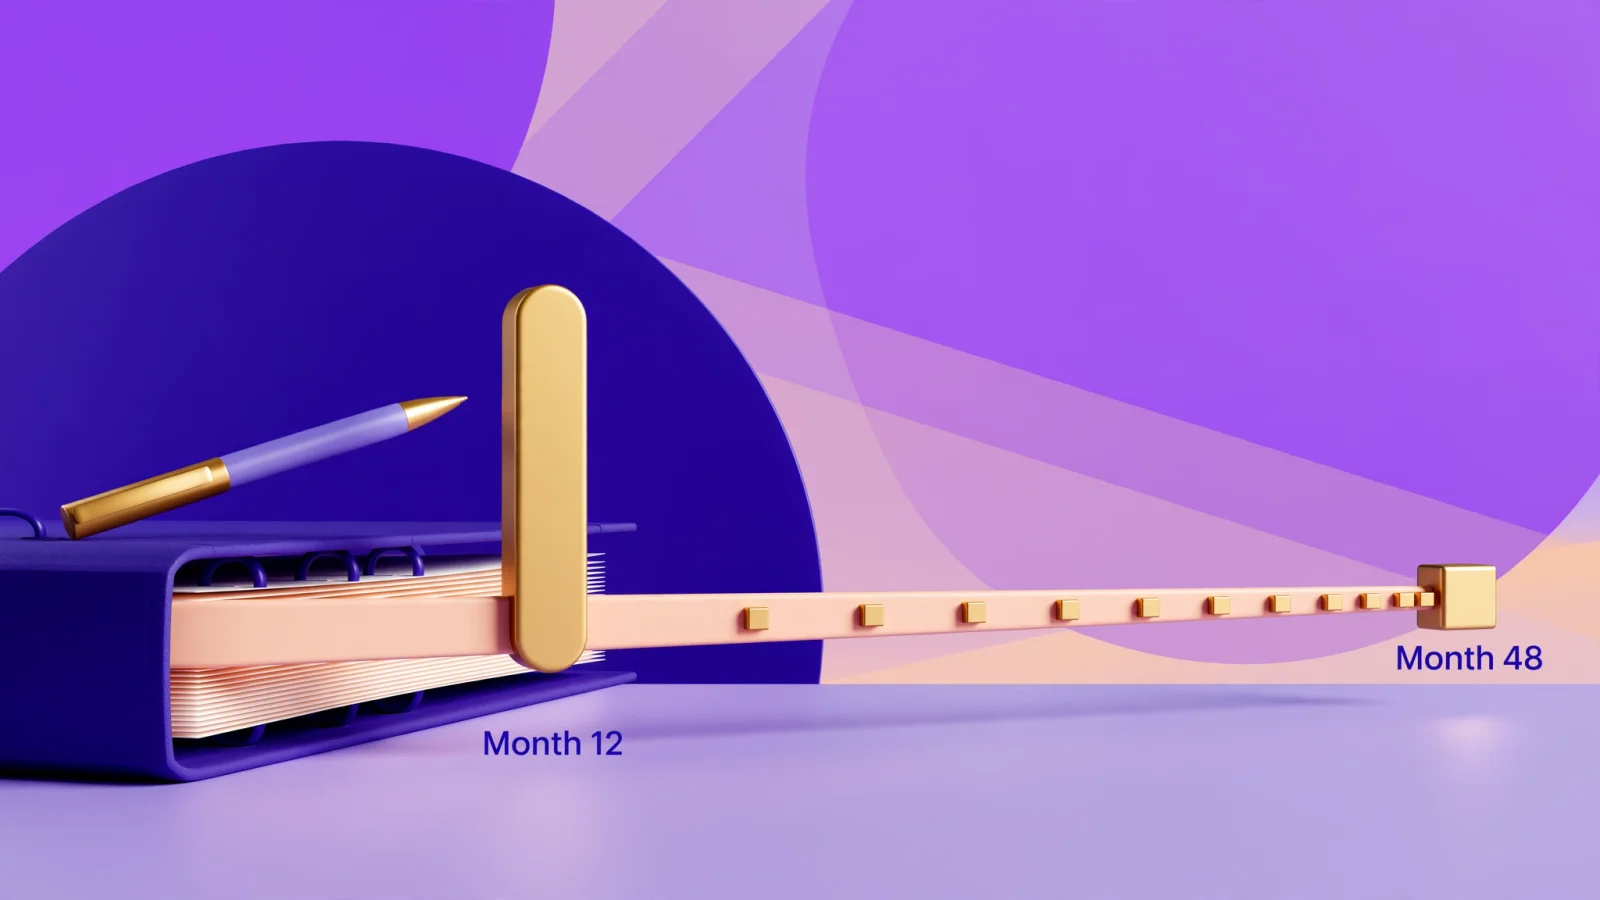
Under the standard cliff structure, no shares vest during the first 11 months of service. The cliff acts as an all-or-nothing threshold, meaning if a founder leaves on day 364, zero shares vest and the company can repurchase the entire grant.
At month 12, the cliff is satisfied and the 25% milestone vests automatically. This figure is the arithmetic result of dividing one year by a four-year schedule. After the first anniversary, the remaining 75% vests in smaller, regular increments over the next three years.
Worked Example: 1,000,000 Founder Shares
Consider a founder issued 1,000,000 shares at formation, subject to continuous service, no acceleration, and no retroactive credit. According to standard corporate models, the vesting progression unfolds like this:
| Service point | Cumulative vested shares | Cumulative vested percentage | Practical meaning |
|---|---|---|---|
| Months 1–11 | 0 | 0% | All 1,000,000 shares remain subject to the unvested-share restrictions. |
| Month 12 | 250,000 | 25% | The one-year cliff is reached. |
| Month 18 | 375,000 | 37.5% | Six months of post-cliff monthly vesting have accrued. |
| Month 24 | 500,000 | 50% | Half of the grant is vested. |
| Month 36 | 750,000 | 75% | Three years of service are complete. |
| Month 48 | 1,000,000 | 100% | The full grant is vested. |
Monthly Versus Quarterly Vesting
After the one-year cliff, the vesting agreement sets a cadence. Monthly vesting gives founders granular credit for their time, so if you leave your startup at month 18 and two weeks, you receive credit for the full 18 months. Quarterly vesting creates larger steps. A founder leaving shortly before a quarterly vesting date can lose up to three months of equity accrual.
Administratively, quarterly vesting reduces the number of cap-table updates a legal team processes. For founders, monthly vesting provides a more accurate reflection of actual time served, though neither approach is legally superior.
Comparing Founder Stock to Employee Stock Options
Restricted Stock and the Repurchase Right
Treating all startup equity as interchangeable leads to cap table errors, because founders generally receive restricted stock at incorporation. You own the shares from day one, vote them, and see them on the cap table. The restriction is a contractual right held by the company to buy back the unvested portion if you leave.
Vesting in this context means the company's repurchase right gradually burns off. Once a share vests, the company loses the right to buy it back upon your departure. The typical repurchase price is the lower of the original cost or the then-current fair market value. Because founders often buy their initial shares at par value, the repurchase price is usually nominal, though your signed stock purchase agreement dictates the exact formula.
Option Vesting and Exercise
Employee stock options operate differently than restricted stock. An option is a right to purchase shares in the future at a set strike price, and vesting determines when the holder may exercise the option to acquire the underlying shares. Unvested options cannot be exercised. When an employee leaves, their unvested options cancel automatically. The company does not need to repurchase anything because the employee never owned the unvested shares.
Why the Security Type Matters for Tax
The distinction between restricted stock and options changes the tax strategy. A Section 83(b) election allows a taxpayer to recognize ordinary income on substantially nonvested property at the time of transfer. You file the election to pay tax on a low initial valuation rather than paying tax as the shares vest and grow in value.
IRS Publication 525 lists statutory and nonstatutory stock options separately from restricted property and includes a section on choosing to include income in the year of transfer for restricted property. Because the publication covers these categories separately, identify the grant instrument before applying the relevant tax rules.
Determining Start Dates and Departure Outcomes
Set the Vesting Start Date
Many founders assume vesting begins on the date of incorporation, but the start date is negotiable. You might work on the concept, build a prototype, and secure early customers for eight months before incorporating the business. The parties can agree to credit that pre-incorporation work by setting an earlier vesting start date.
Similarly, a late-joining co-founder might start vesting six months after incorporation, while a part-time founder could negotiate a custom timeline that shifts when they go full-time. State the exact start date in the signed equity documents, secure board approval, and reconcile the date with the cap table.
Pre-Cliff and Post-Cliff Outcomes
Applying departure mechanics to the previous 1,000,000-share example clarifies how vesting protects the cap table.
At month eight, zero shares are vested, and all 1,000,000 shares remain subject to the repurchase agreement. If the company exercises that right, it pays the required repurchase price and returns the shares to the corporate treasury.
At month 18, 375,000 shares are vested and 625,000 are unvested. The founder keeps the 375,000 vested shares, while the company repurchases the 625,000 unvested shares. The founder remains a significant equity holder despite leaving the operating team.
By month 36, 750,000 shares are vested and the founder retains three-quarters of their original position.
Unvested founder shares do not disappear. Instead, the company can exercise its contractual right to repurchase them, subject to a defined exercise period, purchase price, and payment terms.
Departure Definitions and Repurchase Terms
The circumstances of a departure dictate how equity agreements treat unvested shares. Stock purchase agreements define multiple departure scenarios:
- Voluntary resignation
- Termination for cause
- Termination without cause
- Resignation for good reason
- Death or disability
Cause definitions often focus on serious misconduct, fraud, or a felony conviction. Poor performance, missed product deadlines, or weak leadership rarely qualify as cause under standard venture documents. If a board removes a founder for poor executive performance, that is typically a termination without cause. Unless the equity documents explicitly state a different penalty, a founder removed without cause keeps all shares that vested up to the termination date.
Single-Trigger Versus Double-Trigger Acceleration
How Single-Trigger Acceleration Works
Single-trigger acceleration activates upon one specific event, which is typically a change in control such as a company sale or merger. Upon closing the transaction, a defined percentage of the founder's unvested shares vests immediately. If the agreement provides for 100% single-trigger acceleration, the founder is fully vested the moment the acquisition closes, regardless of whether they stay with the acquiring company.
How Double-Trigger Acceleration Works
Double-trigger acceleration requires two events to execute. A change in control must occur first, followed by the founder experiencing a qualifying termination within a defined post-closing window. The qualifying termination is usually a termination without cause or a resignation for good reason.
If a buyer acquires the startup and fires the founder a month later, the second trigger fires and the unvested shares accelerate. However, if the buyer acquires the startup and the founder voluntarily resigns the next day to start a new company, the second trigger remains unmet. The unvested shares cancel or are repurchased by the buyer.
Terms and Trade-Offs to Negotiate
Compare the two models before finalizing your stock agreements.
| Feature | Single-Trigger Acceleration | Double-Trigger Acceleration |
|---|---|---|
| First Event Required | Change in control (sale/merger). | Change in control (sale/merger). |
| Second Event Required | None. | Qualifying termination (without cause / good reason). |
| Founder Benefit | Guarantees an immediate equity payout upon a successful exit. | Protects the founder from being fired by a hostile buyer shortly after closing. |
| Buyer Concern | Founders have no financial incentive to stay and integrate the business. | Founders retain a strong financial incentive to work for the acquiring entity. |
Single trigger provides immediate protection for founders, though acquiring companies often view fully vested founders as a flight risk if they need them to lead post-merger integration. The buyer frequently requires the founder to re-vest their shares as a condition of the deal, neutralizing the original single-trigger provision. Double trigger balances the scales by protecting you if the buyer replaces you with their own executives, without automatically accelerating your equity because the company changed hands.
When preparing for your financing, negotiate the exact percentage accelerated, the change-in-control definition, the good-reason definition, and the duration of the post-closing protection window. The EverythingVC database helps founders research likely investor profiles, historical theses, and check-size expectations before these conversations begin. Knowing the investor profile allows you to ask targeted governance questions without assuming every firm demands a specific acceleration structure.
83(b), Delaware Documents, and Tax Checkpoints
The 30-Day 83(b) Filing Rule
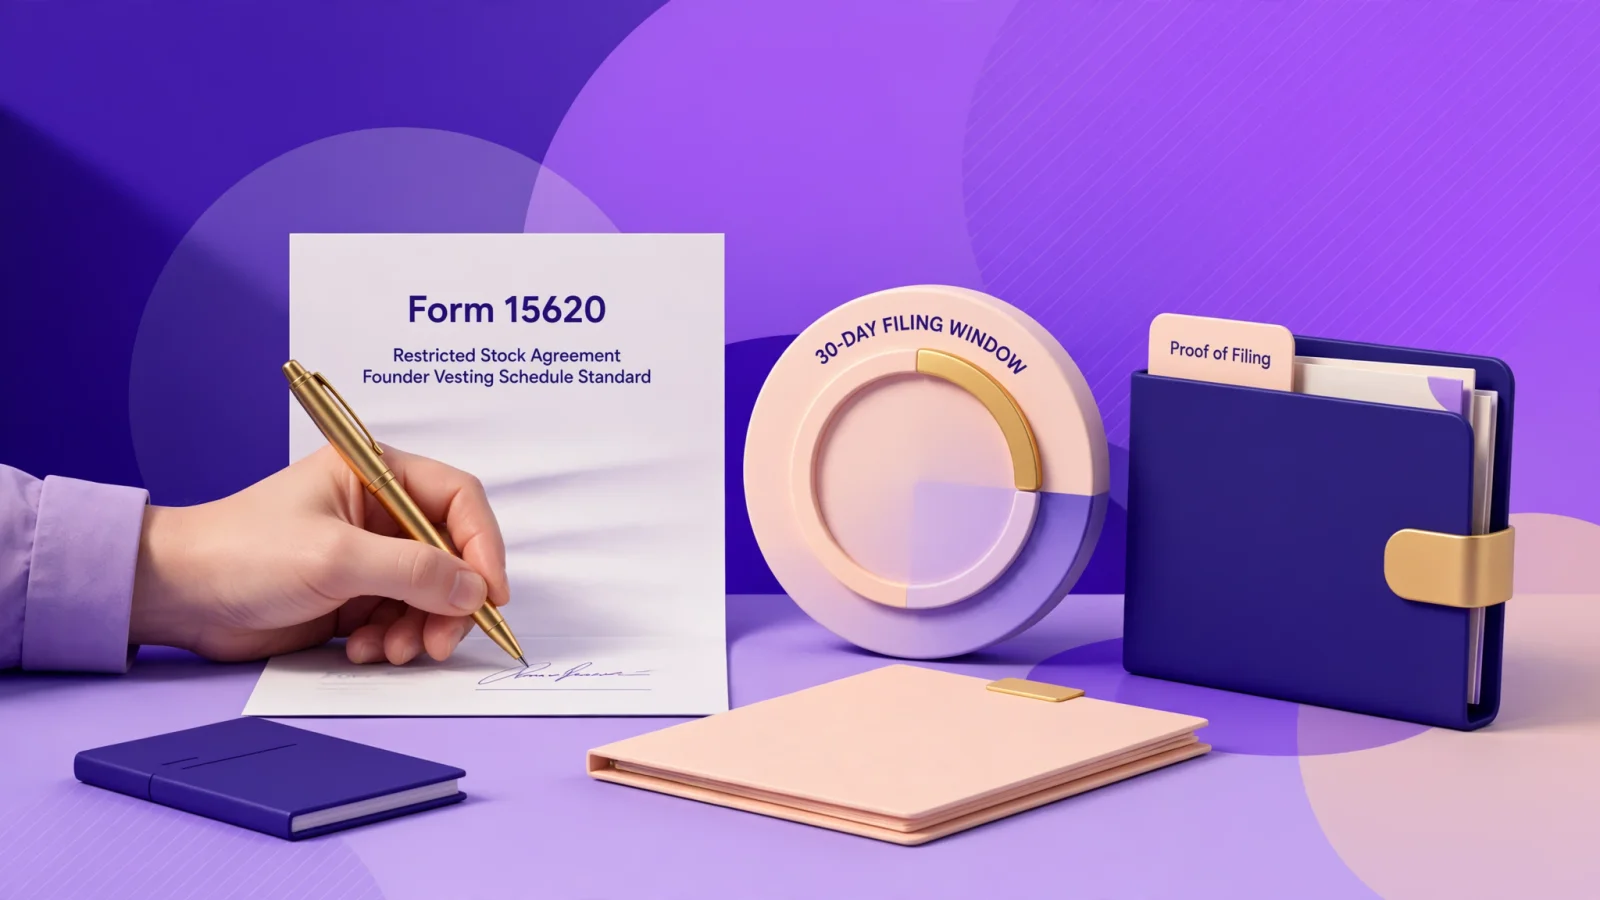
When you receive substantially nonvested property for services, the IRS allows you to include the related income at the transfer date rather than waiting until the property vests. IRS Form 15620 provides the mechanism for this Section 83(b) election.
The deadline is strict, as taxpayers file the election no later than 30 days after the transfer date. If the property transfers on September 17, the thirtieth day is October 17. If October 17 falls on a Saturday, the IRS rollover rule pushes the timely postmark date to Monday, October 19, assuming no legal holiday. Missing the 30-day window generally shifts tax recognition to the standard vesting schedule, based on the shares' value as they vest.
Copies, Proof, and Revocation Limits
The filing process requires multiple steps, beginning with identifying the exact transfer date from your signed restricted-stock agreement. After completing and signing Form 15620, file the paper form with the IRS office where you file your federal return. Consider using certified mail and obtain a postmarked receipt as proof of filing.
The taxpayer then provides a copy of the election to the company, and if the transferee of the property is a different entity, you provide a copy to them as well. Keep copies of the entire package. Filing the election is a permanent decision, as revocation requires IRS consent that is rarely granted. Keep in mind that an 83(b) election does not automatically reduce tax liability. The actual outcome depends on the price paid, the valuation, the forfeiture risk, and your overall tax profile.
Delaware Restrictions and Cap-Table Consistency
Delaware law permits companies to enforce transfer and ownership restrictions. The state allows restrictions to be embedded in the certificate of incorporation, the bylaws, or a stockholder agreement. To enforce these restrictions against a holder, Delaware generally requires a conspicuous notice on the physical stock certificate or the uncertificated-share notice, subject to the statute's actual-knowledge rule.
Your vesting timeline, repurchase rights, and acceleration triggers operate only when they exist in signed corporate documents. A casual email promising a co-founder a certain vesting schedule carries little weight if the board approves a different stock purchase agreement. Reconcile the board consents, the signed founder agreements, the cap-table entries, and your tax filings to ensure they state the identical vesting start date and share count. When evaluating a post-money SAFE valuation cap, investors audit this paperwork to ensure the cap table matches the legal reality.
Founder Vesting Negotiation Checklist and FAQs
Checklist Before Signing or Financing
Review this checklist with legal counsel before incorporating or signing a term sheet:
- Confirm the total vesting period and cliff duration.
- Verify the vesting cadence after the cliff (monthly versus quarterly).
- Document the exact vesting start date.
- Calculate and clearly state any retroactive pre-incorporation credit.
- Identify the security type (restricted stock versus options).
- Confirm the company holds the repurchase right.
- Note the repurchase exercise period and purchase price formula.
- Review departure definitions for cause, without cause, and good reason.
- Verify the treatment of vested and unvested shares upon departure.
- Confirm the acceleration trigger (single versus double) and percentage.
- Record the property transfer date and track the 30-day 83(b) deadline.
- Ensure board approvals match the cap-table software.
VC and LP Diligence Questions
Early-stage investors review founder retention and cap-table risk extensively. If you target the best seed funds for first time founders, expect thorough diligence on your equity structure.
Venture capitalists audit founder ownership percentages and vesting start dates while confirming the company holds a valid repurchase right over unvested shares. They check acceleration provisions to ensure they avoid a retention crisis in a merger scenario, and verify that termination definitions match the tax records.
Limited Partners also treat founder vesting as a portfolio-level governance issue. During fund diligence, LPs ask if the fund manager identifies founder-retention risks and ensures equity arrangements are documented before deploying institutional capital. Institutional backers want to see a clear portfolio-company process for handling founder departures and repurchasing equity.
Frequently Asked Questions
Is four-year vesting mandatory for founders? No. It is a common market structure rather than a statutory requirement. The actual rules governing your equity live in your company's specific agreements.
What does a one-year cliff mean? No shares vest before the first anniversary. Once you hit that anniversary, a calculated milestone, typically 25% for a four-year schedule, vests immediately.
Do founders receive their shares upfront? Founder stock is usually issued near formation. You own the shares, but they remain subject to the company's right to repurchase the unvested portion if you depart.
What happens if a founder leaves before the one-year cliff? Under the standard schedule, zero shares have vested. The company retains a contractual right to repurchase the unvested shares and return them to the corporate treasury.
Can founders receive credit for work before incorporation? Founders can negotiate retroactive vesting credit for early work. Document the specific start date in the stock purchase agreement rather than relying on a verbal promise.
Is monthly vesting better than quarterly vesting? Monthly vesting gives a more granular accrual for actual time served. In contrast, quarterly vesting limits the number of cap-table updates a company performs.
What is the difference between single-trigger and double-trigger acceleration? Single-trigger acceleration requires only one event, typically a sale. Double-trigger acceleration requires a sale followed by a qualifying termination within a set period.
When must a founder file an 83(b) election? The IRS requires the election to be filed no later than 30 days after the property is transferred.
Does an 83(b) election apply to stock options? The IRS states that the election cannot be made for a statutory or nonstatutory stock option.
EverythingStartups builds specialized databases and tools to help you understand the early-stage funding ecosystem. Whether you are a founder preparing your cap table for institutional diligence or an investor evaluating team continuity, our actionable market intelligence connects you to the right data. Explore the weekly newsletter, the premium EverythingVC database, and our startup resources at EverythingStartups to track capital movement and refine your fundraising strategy.


